The number that decides everything
Three figures settle this. What the Selden house is worth, what is secured against it, and what you owe elsewhere.
We can give you the first in writing within 24 hours at no cost. The second comes from your servicer and a title search, and your attorney can order one. The third you already know. Until all three are in front of you, selling the house is a feeling rather than a plan, and a decision this size deserves better than that.
What else to try before selling to clear debt
The specific case worth pausing on: selling a house to pay unsecured debt that a bankruptcy might have discharged anyway. That happens, it is expensive, and it is avoidable with one conversation.
Equity in a home receives certain protections. Cash from a sale is treated differently. Which is to say the order in which you do things can change the outcome substantially, and a bankruptcy attorney will tell you that in an hour. Ask before the house goes under contract.
The Selden market underneath this
The median is up 9.86% year over year as of 2026-10. A firming market gives you a little room for error on price, which is worth more than it sounds when the house is not in showable condition. At a $637,173 median, Selden is a market where buyers expect to do some work. That helps a seller with a dated house and hurts one with a genuinely broken one, because the pool that will take on a project is not the same pool that will take on a gut. The median house here goes under contract in about 23 days, which is quick for Long Island. It is also a figure that only applies to property in showable condition.
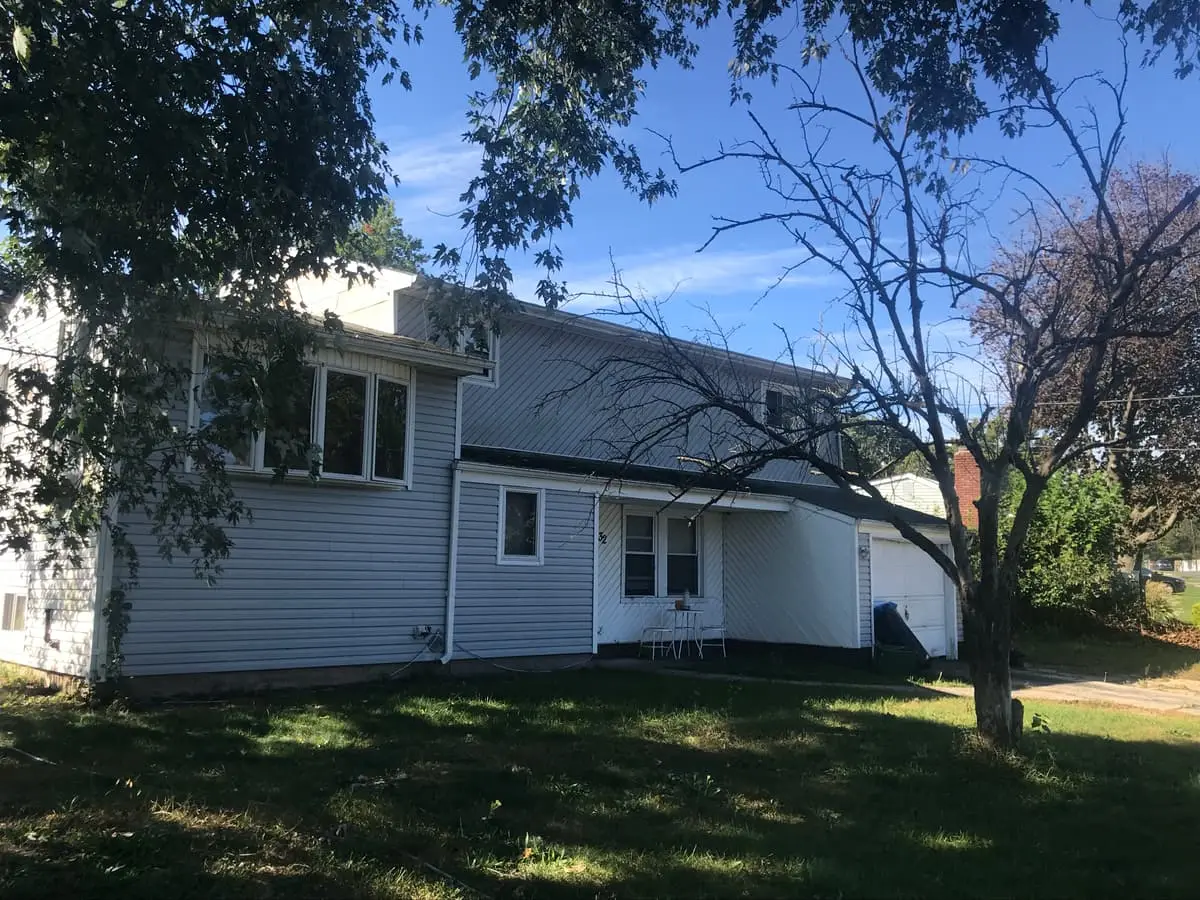
A four-bedroom on Corvette Road. In Selden, bought and paid for by us.
Debts already secured against the Selden house
A title search will show what is secured against the house, and people in debt are sometimes surprised. Judgments from creditors, a contractor's mechanic's lien, unpaid property taxes, and anything a lender filed all attach to the property and get paid at closing.
That matters because it changes what the sale nets you rather than whether it can happen. These normally get resolved out of the proceeds as part of an ordinary closing. Your attorney orders the search, and it is worth doing early rather than discovering a judgment the week of closing.
Why a failed sale costs a Selden seller in debt more
Interest does not pause while a listing runs. Whatever your balances are costing per month, multiply that by the length of a retail sale in Selden and put it next to the difference in price. Sometimes the listing still wins comfortably. Sometimes it does not, and people are surprised which.
Do that arithmetic before you choose a route. It is the one calculation specific to selling for debt, and it is the one nobody runs.
What the two paths cost in Selden
These are the two routes open to you with a house with debt behind it, priced against what Selden houses actually sell for.
Work it against Selden's own numbers. The median sale here is $637,173. A 5% commission on that is $31,859, and seller closing costs of about 2% add roughly $12,743. Those are costs we can cover on our side. That is $44,602 gone before anyone counts the repairs it took to get the house listable.
There are two waits in a listed sale and people usually only count the first. In Selden the median house takes about 23 days to go from listed to a signed contract. Then it waits again, typically 45 to 60 days, while the buyer's lender orders an appraisal and underwrites the loan. Call it 68 to 83 days from sign to keys, assuming nothing goes wrong.
The part worth understanding is what a signed contract actually guarantees, which is less than most sellers assume. A retail buyer with a mortgage contingency can walk away right up to the end. If they do not qualify, if the appraisal comes in under the price, if they change their mind and let the financing lapse. A share of deals die exactly there, after months of waiting, and the house goes back on the market with time on it. We are not borrowing anything, so there is no lender to satisfy, no appraisal to come in low and no contingency to exercise.
| Listing with an agent | Selling to us | |
|---|---|---|
| Sale price | $637,173 (Selden median) | Our written offer |
| Commission | −$31,859 | None |
| Seller closing costs | −$12,743 | We can cover them |
| Repairs before listing | Out of pocket | None |
| Cleanout | Yours | Ours |
| Showings | Until it sells | One visit |
| Listed to signed contract | 23 days (Selden median, once listable) | 24 hours to a written offer |
| Contract to closing | 45 to 60 days (waiting on the buyer's lender) | A date you choose |
| Total wait | 68 to 83 days if nothing falls through | Yours to set |
| Can the buyer walk? | Yes (mortgage contingency runs to the end) | No financing to fall through |
| Before repairs and carrying | $592,571 | The number we put in writing |
For the listing side we have used a 5% commission and about 2% in seller closing costs; your real figures may differ. Repairs and carrying costs are left out because they depend on the house. If yours is in good shape, a good agent may well get you more than we would, and we will tell you if so.
Plan what the proceeds pay before you close
Secured debts come off at closing automatically. Everything else is up to you, and it is worth deciding before the money arrives.
Get a written payoff figure from each creditor, not a statement balance. Some creditors will accept a lump-sum settlement for less than the balance, and a nonprofit credit counselor can tell you whether yours are likely to. Ask a CPA whether any of the sale is taxable before you plan the money, so a tax bill does not become the next debt.
How selling a house with debt behind it in Selden works
- 1
You tell us about the house
An address in 11784 and a rough idea of condition. Two minutes on the phone or the form. We do not need photographs, a clean house, or anything fixed first.
- 2
One short visit
One of us comes by once, usually for less than half an hour. On a ranch or hi-ranch like most of Selden, what we look at closely is the roof, the boiler and the wiring, not the finishes.
- 3
You see the number
Within a day you get our offer as one written figure. Get a Suffolk County agent's opinion alongside it if that helps. For a house that could go on the market as it stands, listing may come out ahead, and we will tell you if so.
- 4
You pick the closing date
Fast if you need fast, or months out if you are waiting on probate, a tenant, or somewhere to move to. Either way you skip the 68 to 83 days a listed Selden house spends finding a buyer and then waiting on that buyer's mortgage.
Moving out of the Selden house on a date that works
The debt is only half of it. The other half is where you go next, and it deserves a real plan: what rent or payment you can carry once the debt is gone, and where.
Sort that out first, then choose a closing date that gives you time to move. We work to the date you need. You do not have to empty the house or clean it, and anything you leave behind is ours to deal with after closing.
Common questions
Will selling the Selden house clear my debt?
That depends on three numbers: what the house is worth, what is secured against it, and what you owe elsewhere. The mortgage payoff and any liens come off first. Get all three on paper before deciding, because the amount actually available is frequently lower than people expect.
Should I talk to anyone before selling to pay off debt?
We would suggest it, and before you speak to buyers. A HUD-approved housing counselor can look at the mortgage side, a nonprofit credit counselor at unsecured debt, and a bankruptcy attorney if the sums are serious. Two of the three are free.
What if there are judgments or creditor liens against me?
A judgment that has attached to the house is normally paid off from the proceeds at closing. That is routine and does not stop the sale; it just means less reaches you. Ask your attorney to order a title search early so there are no surprises close to the closing date.
What if the house is worth less than the debt secured on it?
In that case it becomes a short sale, which needs the lender's agreement to take less than the full payoff. It is something we can work through with you, and there is a separate page on it. Get the payoff amount in writing before anything else.